Diversified credit outlook 2027: Patience pays in a higher-rate world

Key takeaways
- A higher and more uncertain rate environment and persistent inflation will test investors’ ability to differentiate between borrowers in a challenging operating environment.
- A period of stress in Australian real estate credit can create opportunities for patient, long-term investors in a dislocated market.
- Asia’s maturing credit markets are structural opportunities for investors focused on quality borrowers and long-term megatrends.
The past year has seen investors contend with surprising monetary policy changes and inflation expectations firmly establishing themselves as risks. In a higher-rate world, we look to capture opportunities as the cost of credit is repriced across the broader Asia-Pacific region. Investors, however, will need to be selective in this changing environment, and we believe those focusing on quality, reliable borrowers will be able to withstand 2027’s turbulence.
Investors had to adjust their rate expectations multiple times throughout 2026. Five interest rate increases by the Reserve Bank of Australia as of November 2026 have brought the cash rate to 4.85%, the highest since 2008. The US Federal Reserve has also raised interest rates for the first time since 2023.
Policy will remain a source of uncertainty going into 2027. In Australia and in many developed markets, central banks will stay on guard against the threat of inflation, fuelled by supply chain disruption and geopolitical tensions.
This backdrop holds mixed blessings for diversified and private credit. While higher rates can put pressure on corporate balance sheets, higher yields mean that investors need to take less risk to meet their return targets, and may have an opportunity for high single-digit returns in both Australia and less mature markets across Asia-Pacific.
Monetary policy is normalising in major economies including the US and Japan, and higher energy prices are keeping inflation on the agenda.
A new normal for borrowing costs: Higher-for-longer rates favour private credit
After a year of policy surprises, we are facing a higher and more uncertain rate environment. Inflation risks limiting the scope for sustained monetary easing in major economies including the US and Japan, and higher energy prices are keeping inflation on the agenda. Heightened geopolitical risk and fiscal deficits – especially in the US – also mean investors are likely to demand a greater term premium, keeping benchmark yields elevated. The challenge will increase as a result of the significant funding needed to support the expansion of AI-linked data centres.
In Australia, we see the greater risk not as an inflationary spiral but as stagnation, in which low growth prevents businesses from passing on rising costs and squeezes margins.
Private credit is well placed for this environment. Unlike the public bond markets, floating-rate loans reset higher as base rates rise. Relatively short tenors also provide investors with repricing power should spreads move more dramatically.
The key question is whether borrowers can cope. Higher rates and rising costs are negative for corporate balance sheets, but we expect greater differentiation. Companies with genuine pricing power will pass on higher costs, while others will have to accept narrowing margins, resulting in higher credit risk. To paraphrase Warren Buffett, it is only when the tide goes out that you discover who has been swimming naked – and rising interest rates are often a sea change for corporate credit.
For investors, higher yields change the risk-reward calculation. With government bond yields also pushing higher, we are alert to attractive risk-adjusted opportunities across the credit spectrum, including in public markets and structured credit.
Australian real estate credit: Finding value amid disruption
These dynamics, coupled with signs of stress in the Australian corporate sector, are likely to spur a flight to quality in Australian credit.
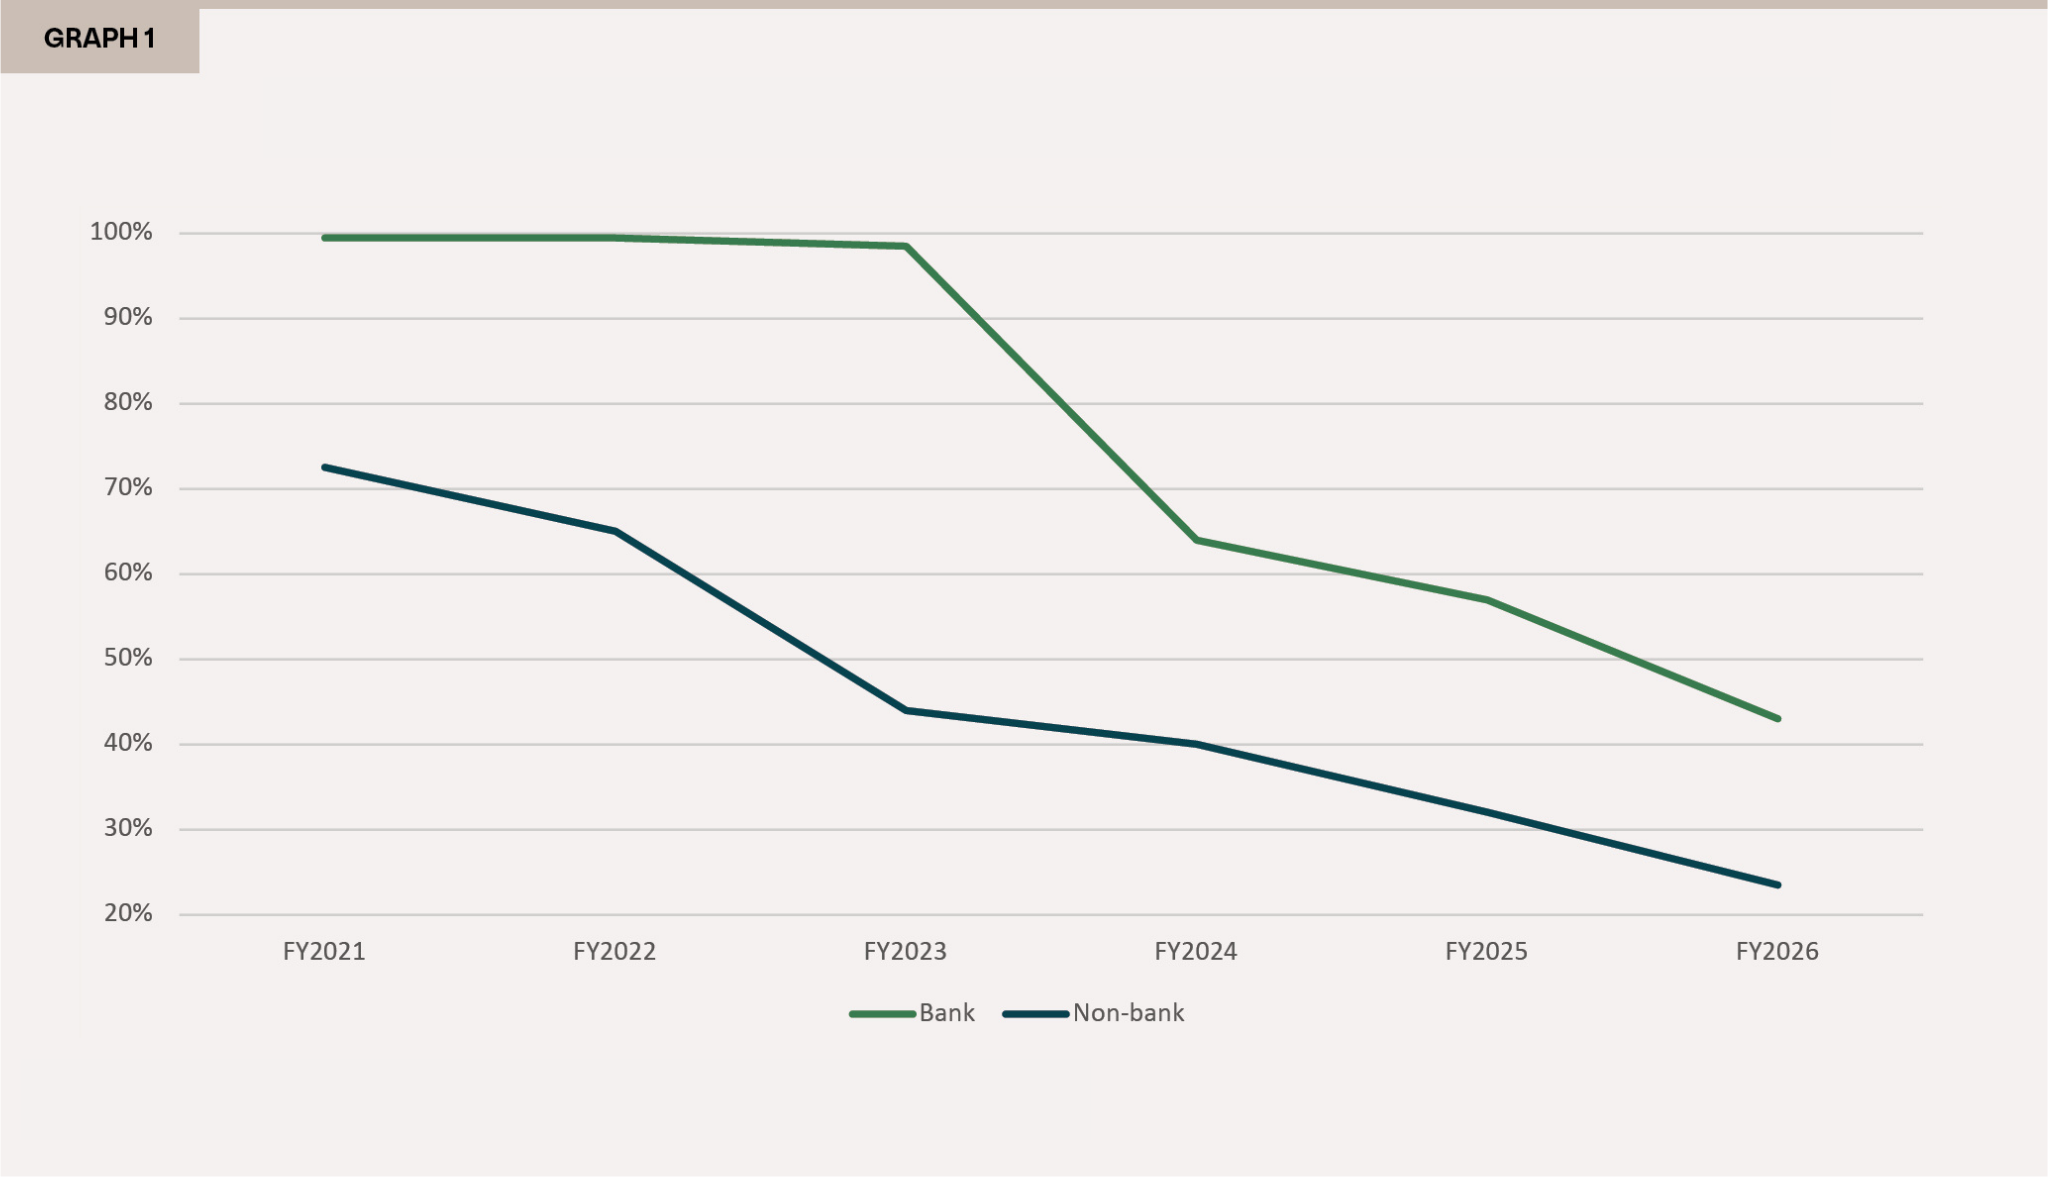
The recent collapse of a Sydney developer owing more than A$3 billion to around 40 private lenders is one of the largest construction insolvencies in recent Australian history.1 The insolvency has led private credit investors to refocus on the capability of lenders to assess risk within a rapidly changing market landscape. A continued softening of the Australian residential housing market will present opportunities for lenders able to navigate these risks. Banks traditionally granted development loans subject to full presale debt coverage. In recent years, the number of units covered by presale has declined to less than half due to increasing competition arising from strong capital inflows into bank and non-bank lenders.
Graph 1: Non-banks maintaining a gap against banks on presale debt coverage requirements
Source: Ashurst Perkins Coie Australia Real Estate Finance Market Update 2026
Developers who obtained financing with low presale requirements in 2023-24 will have to refinance unsold units into residual stock loans, and with presale levels in the following years even lower (Graph 1), we expect demand for the residual stock loan market to grow further in the near term.
It will be up to lenders to assess what the appropriate risk premium should be for a residential development or residual stock loan in a slowing housing market. Regulators are also paying attention: ASIC Commissioner Simone Constant warned in September that "the first significant cracks" are beginning to emerge, as the sector's weaknesses are tested at scale for the first time.2
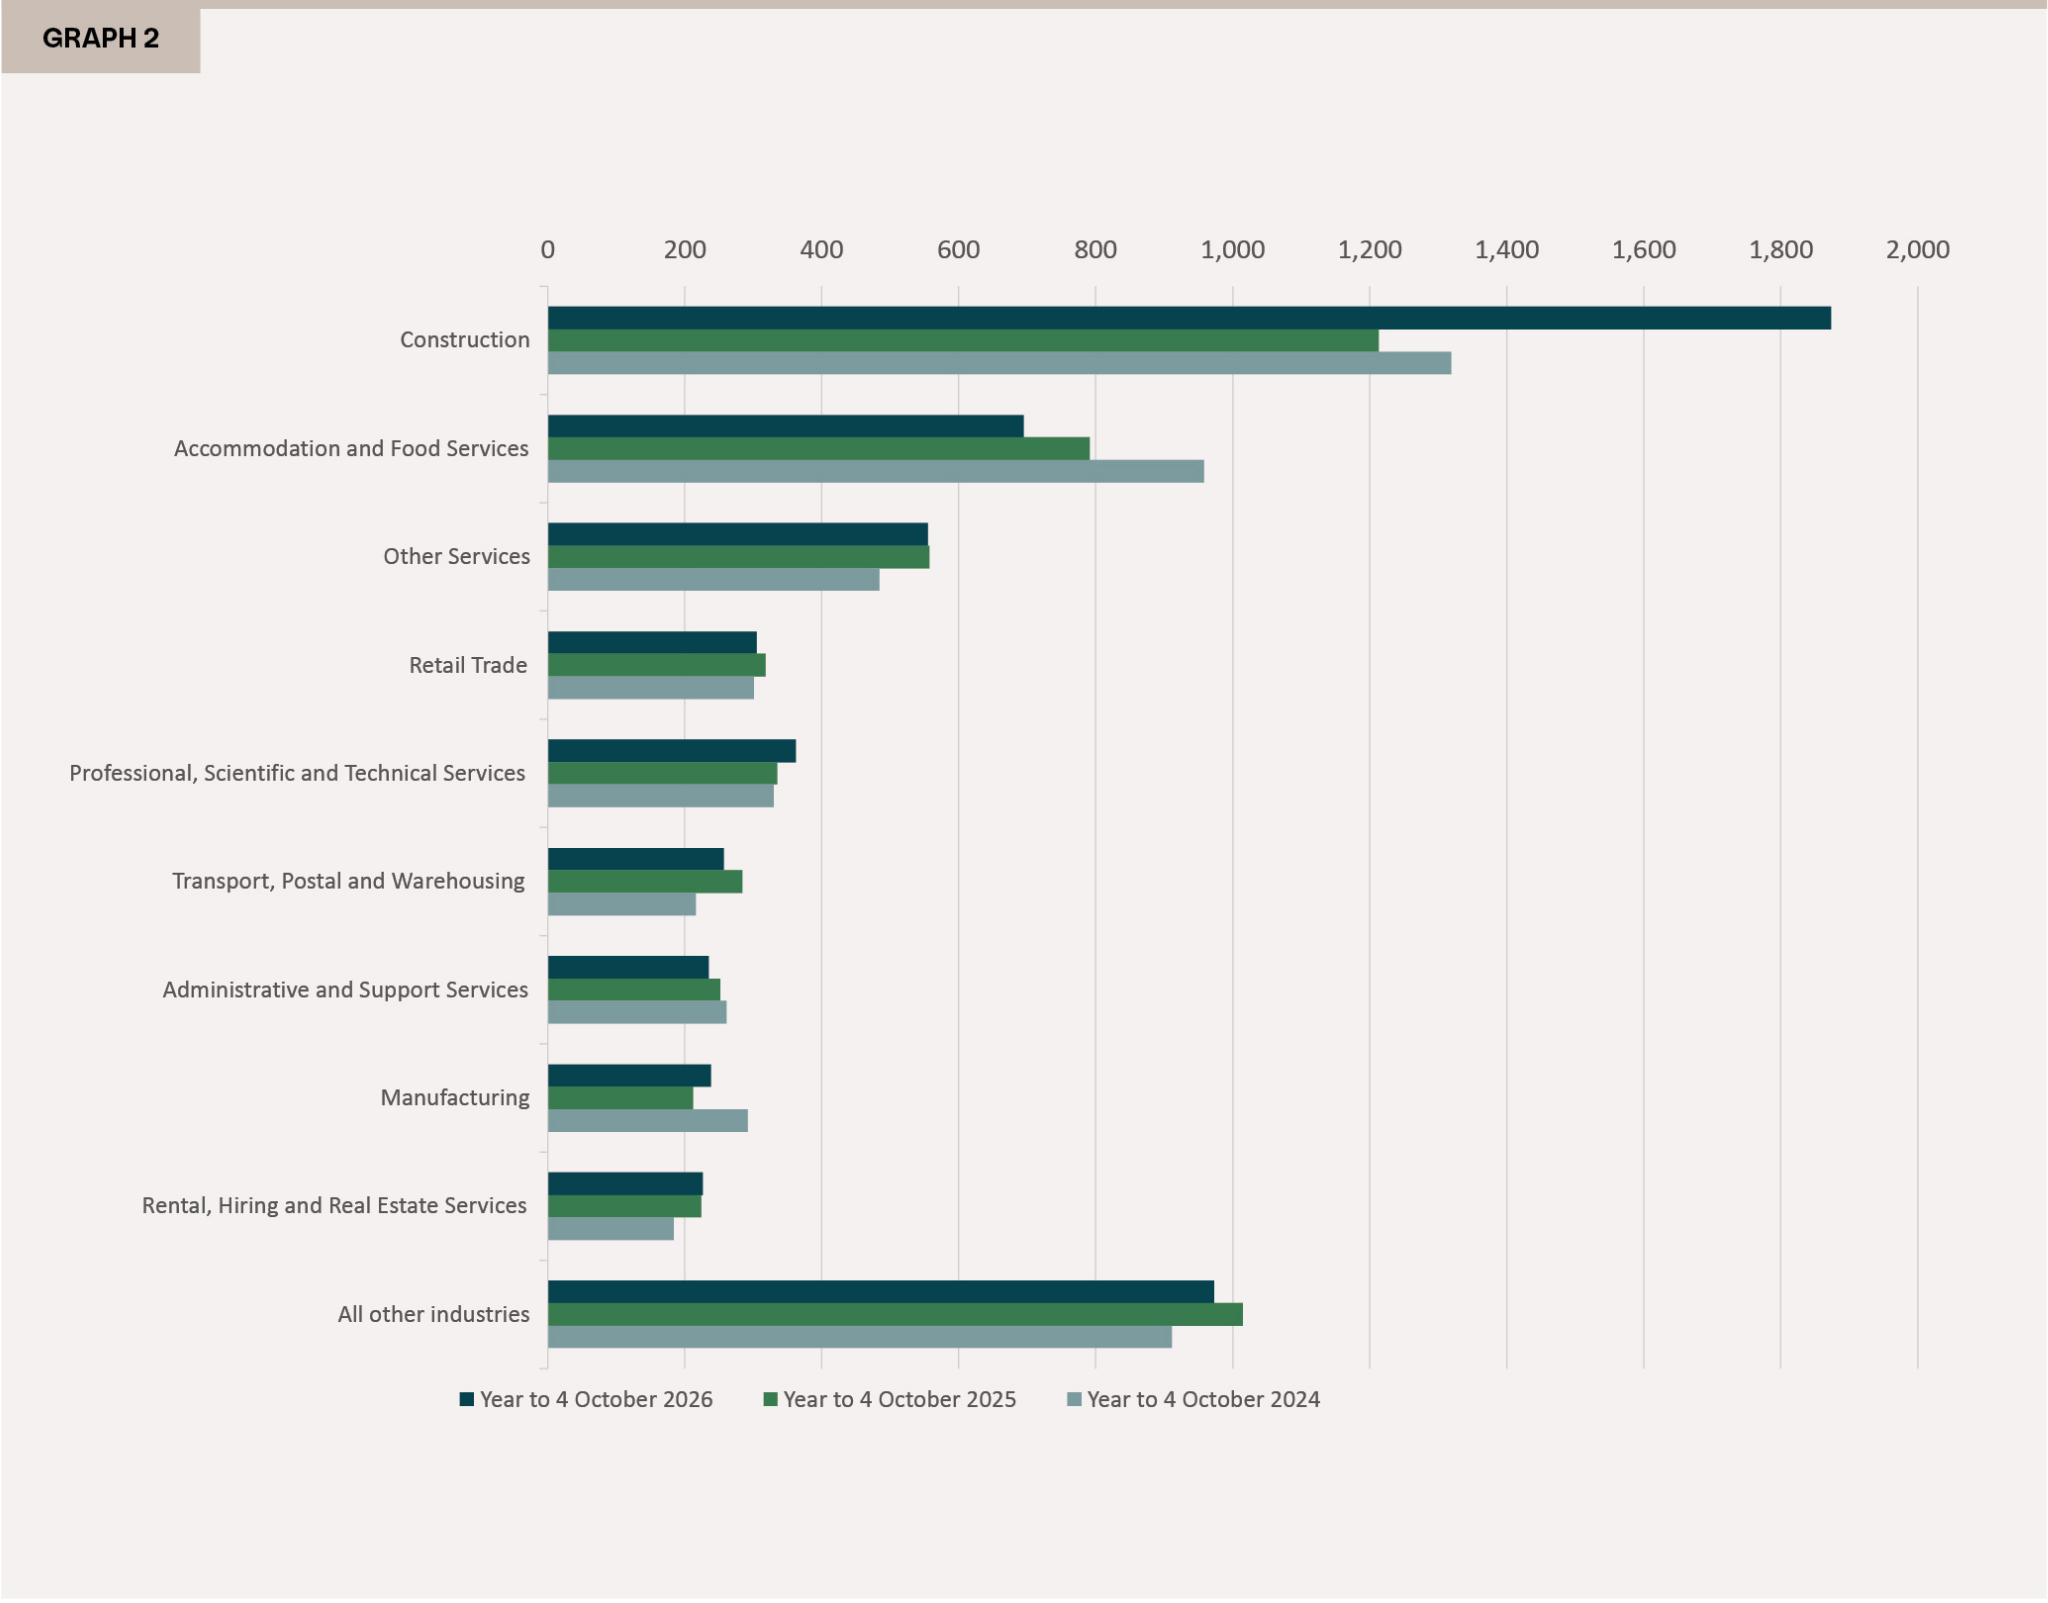
Graph 2: Construction leads a rise in Australian corporate insolvencies
Source: ASIC Australian insolvency statistics
We expect a period of consolidation of lenders in Australian private credit as the market absorbs these stresses. Examples of gating at semi-liquid investment vehicles could also weaken sentiment towards the sector.
We believe long-term investors can view this adjustment not as a cause for alarm but as a healthy shake-out in a rapidly growing market. The growth of private credit in Australia has mirrored global trends, and it is worth noting that similar stresses elsewhere have not dented enthusiasm for private credit as an asset class.3
We also take comfort from historically low default rates and broad diversification in Australian corporate credit, where technology-related borrowers make up a much smaller slice of the overall pie than they do in the US, for instance. Patient, well-capitalised investors will have plenty of opportunities to find value in a dislocated market.
Private equity-led refinancing can be another potential source of opportunity. With muted M&A activity and limited access to the IPO markets, many private equity firms are looking to refinance existing agreements on amended terms. Refinancings – rather than new-money investments – have also dominated syndicated loan volumes in the US and Europe over the past year.
Competition among lenders has allowed pricing on these refinancings to grind tighter. Where lenders have hit their return floors, we have seen cases where some are willing to give ground on terms, accepting looser covenants or weaker collateral requirements. Higher rates and a renewed focus on quality are likely to limit this trend, presenting more compelling opportunities for long-term investors.
Riding the AI investment wave in 2027
The scale of investment in data centres is transforming credit markets globally – and Asia-Pacific is no exception.
Data centre deals have become much larger, with A$1 billion-plus projects now increasingly common. Developers are beginning to explore GPU financings and securitisation to meet surging demand for capital. Grid upgrades and energy projects are rising up the priority list.
We see significant opportunities in this area, with two key concerns. The first one is the default risk on more marginal projects, if construction schedules slip or end-customers fail to monetise their AI investments. The second is the risk of a crowding-out effect as financing for the AI build-out competes with other investment requirements, potentially pushing spreads higher across all credit segments.
We mitigate these risks by focusing on fundamentals and investor protection. In digital infrastructure, we concentrate our attention on top-tier borrowers and established assets, resisting the temptation to chase returns. Bankability is a priority – in credit as much as in other asset classes.
Asia as a growth engine
Asia also stands out as a relative value play and structural opportunity. Economic growth and bond yields are attractive, and we believe there is a premium to be earned from emerging Asian markets relative to developed markets. Many of the region’s emerging economies have proven their resilience in 2026 despite reliance on imported fuel and tariff-induced supply chain disruptions fuelling inflation. As economies in the region mature and move through their own cycles, financing is becoming more sophisticated, with notable growth in non-bank credit.
Asia-Pacific private credit is projected to grow by nearly 56% to US$92 billion in the four years to 2027, according to the Alternative Investment Management Association.4 Even so, the region remains underpenetrated: it accounts for more than a third of global GDP but only around 6–7% of global private credit assets, and its companies still rely heavily on bank lending.
The AI build-out is also accelerating this structural transformation in Asia. Banks remain the dominant source of credit in the region, but their capacity to fund new projects is not limitless. As banks look to recycle their capital, we expect non-bank lenders to play a greater role in the region’s credit markets.
Is a return of M&A creating credit opportunities in 2027?
Early signs of a rebound in M&A activity point to the upside potential for private credit across Asia-Pacific.
Higher rates will accelerate the revaluation of growth businesses and could close the valuation gap between buyers and sellers. International interest in Asia-Pacific is also growing.
While not our base case, we expect to see more lending opportunities across corporate credit if M&A bounces back strongly.
The data so far shows how much ground there is to make up. In Australia and New Zealand, announced M&A deal value fell by one-third in the 2026 financial year to around US$83 billion – its lowest level in a decade and well below the record US$246 billion of four years earlier – even as global dealmaking rose 45% over the same period.5 The absence of large deals was the most notable feature, and inbound transactions fell to their lowest level since 2017.
Looking ahead to 2027, higher yields offer opportunities, but borrower resilience will remain critical. Stress in parts of the Australian market, the AI build-out and Asia’s maturing credit markets each present scope for patient investors to find value, alongside risks that demand careful assessment. Across these opportunities, our focus remains on quality borrowers, disciplined pricing and strong investor protections. In a normalising world, patience means being ready to act when those fundamentals align – not chasing returns at the expense of lending standards.
[1] Primrose Riordan, Max Mason (2026), Bathla’s collapse is slowly revealing a long trail of shadow lending
[2] Australian Securities and Investments Commission (2026), The case for private credit standards: if not, why not?
[3] Preqin (2026), Private Credit Q2 2026: Preqin Quarterly Update
[4] AIMA (2025), Report highlights Asia-Pacific’s growing global private credit market
[5] Boston Consulting Group (2026), Australia and New Zealand M&A 2026: Headwinds Call for Targeted Dealmaking
Lillian Nunez
Lillian joined IFM Investors in 2007 and is a Co-Head of the APAC Diversified Credit team, within the Debt Investments Group. Lillian leads the team responsible for conducting credit analysis, due diligence, investment recommendations and portfolio management support.
Hiran Wanigasekera
Hiran is an Executive Director and Co-Head of IFM Investors' APAC Diversified Credit capability. He responsible for joint management of key credit portfolios, credit product strategies and managing the day-to-day running of debt portfolios. Hiran has worked across a wide range of credit sectors and industries including bank lending, corporate credit and structured investments.

Private Markets Macro Outlook 2027: AI, energy and a less predictable world
Much of what happens in 2027 will come down to two things: how fast AI investment keeps growing, and how often energy supply is disrupted. Neither is easy to forecast, which makes resilience in portfolio construction more important than any single call.